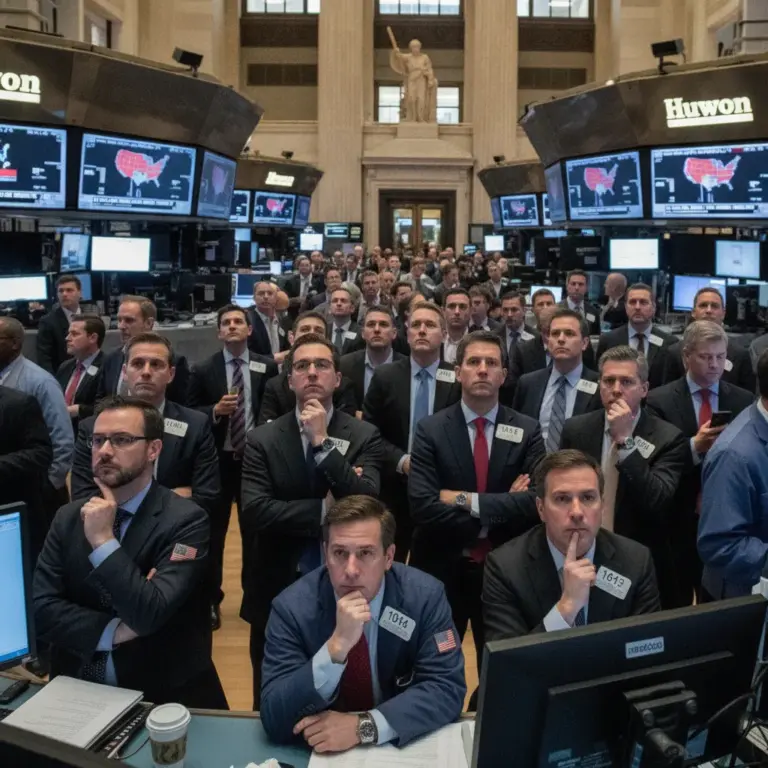
Wall Street experienced a brutal shakeup this week as fears over potential new artificial intelligence regulations triggered a massive sell-off in tech and semiconductor stocks. The fallout was widespread, with the Dow Jones Industrial Average plummeting more than 1,800 points and the Nasdaq sinking deep into correction territory. For millions of Americans glancing at their 401(k) statements, these red numbers have sparked immediate anxiety about the safety of their long-term savings.
Financial advisors are urging investors to keep a cool head despite the turbulence. Mark J. White of Mark White Wealth Advisors warns that the greatest danger during such swings isn’t usually the dip itself, but the tendency to make impulsive, emotion-driven decisions. For younger workers, this slump might actually serve as a silver lining, allowing them to snap up shares at discounted prices through their regular contributions before the market eventually recovers.
However, the situation is far more precarious for those standing on the doorstep of retirement. Jay Duffy, managing partner at Frame Wealth, notes that people in their early sixties may find themselves trapped in aggressive portfolios meant for much younger investors. When retirees are forced to sell assets during a crash just to pay for daily living expenses, they face sequence-of-returns risk, a dangerous cycle that can drain a nest egg much faster than anticipated.
To mitigate these risks, experts suggest maintaining a healthy buffer of cash and conservative holdings to cover short-term needs without touching volatile stocks. Rather than panicking or ignoring the problem entirely, investors are encouraged to rebalance their accounts so their risk levels align with their actual retirement dates. Ultimately, a sturdy portfolio should be built to weather these storms without requiring a total overhaul every time the market hits a rough patch.